The discussion surrounding batteries in the Greek electricity system has already highlighted their importance for the better utilisation of renewable energy sources and the limitation of curtailments. Interest has now shifted to whether storage projects can transition from planning to implementation and constitute viable investments.
Progress, however, is judged not only by the number of permits or the capacity of the projects being planned, but also by their feasibility of implementation and grid connection, operating conditions, and financial return prospects.
Real progress behind the numbers
The landscape of the storage market in Greece varies significantly depending on the stage of project development. According to the IPTO registry for April 2026, there were 42 installations with a total capacity of 1.6 GW, which either held a connection offer or were already in operation on the transmission system.
Conversely, broader licensing activity is reflected in the data from MitOS, the information platform for the licensing of storage projects. According to the record updated on 20 October 2026, the RAAEY registry included 1,580 storage installations with a total capacity of 65.3 GW.
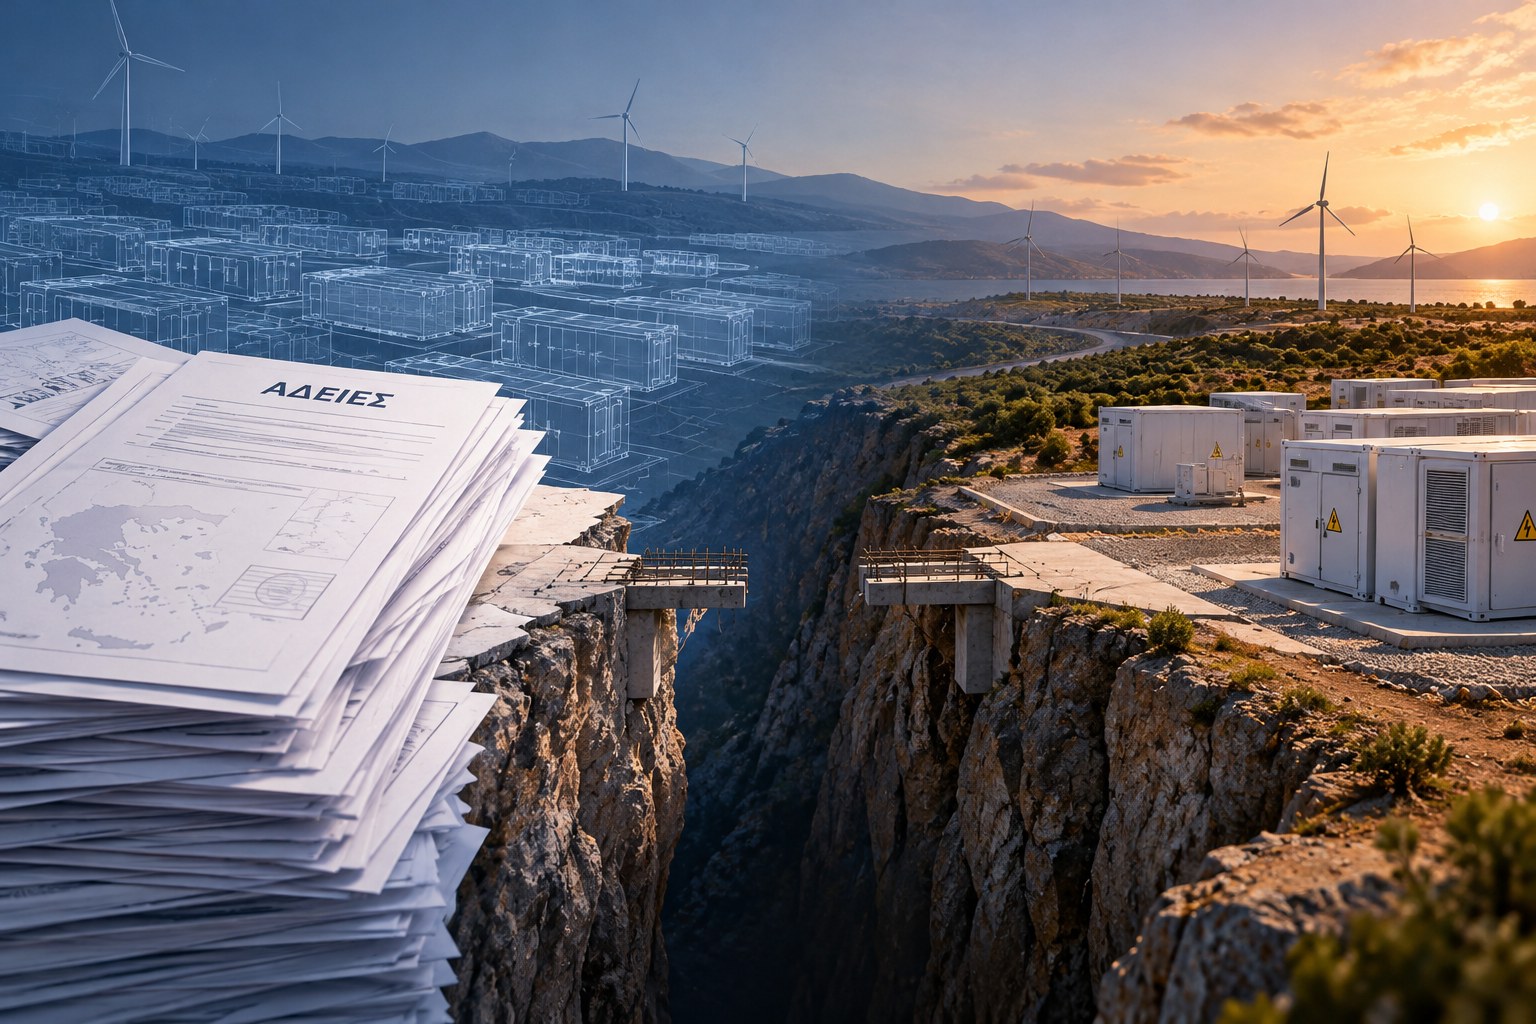
The two figures are not directly comparable, as they concern different stages of development, different reference dates and a different scope of coverage. The gap between licensing and implementation, however, highlights a critical issue.
The total capacity shown in the registries does not, in itself, reflect the actual storage capacity available in the system. To assess market progress, it is necessary to examine those projects that secure grid connection, complete their construction and commence commercial operation.
The difficult transition from planning to implementation
The transition from the licensing process to commercial operation requires addressing a series of practical and financial issues. Available grid capacity, connection terms, financing, equipment costs, and the regulatory framework affect the implementation timeline as well as the characteristics of each investment.
Furthermore, the installation of a battery does not automatically mean it will operate in a way that maximizes its value for the power system. Charging and discharging must be adapted to generation and demand conditions, market prices, and the technical capabilities of the installation.
The difficulties in implementing storage projects are also highlighted in the European Commission’s 2026 report on Greece. As a characteristic example, the report mentions the “Ptolemaida Battery Energy Storage System” project, which, at the time of drafting the report, was facing delays primarily due to licensing issues and difficulties in procuring equipment. Its completion was scheduled for 2027. This case demonstrates that, even when investment plans and financial support are in place, the transition to the construction and operation phases is not guaranteed.
Therefore, evaluating the development of the sector requires more than simply counting projects. Installed capacity, the actual availability of the systems, as well as the energy they absorb from or inject into the grid, constitute distinct indicators, each describing a different aspect of their operation.
What does the operation of storage systems so far show?
The first available data from the operation of storage systems in Greece offer a picture of both their capabilities and their limitations. According to The Green Tank’s analysis for August 2026, the capacity of standalone storage systems that had been put into operation stood at 600.18 MW.
For August, data from IPTO’s ISP2 and ISP3 market clearings show that batteries absorbed 51.6 GWh of electricity and injected 44.9 GWh into the system. According to the same analysis, their operation contributed to avoiding RES generation curtailments amounting to 28.8 GWh, a quantity corresponding to 15.4% of the month’s total curtailments.
These figures demonstrate that batteries can already contribute to utilising energy that would otherwise be lost. However, they do not constitute proof that the problem has been solved. The data concern a specific period and are based on design data and estimates. They should not be interpreted as an indication of consistent performance for every month, nor as a measure of the country’s overall storage adequacy.
Furthermore, the energy returned to the grid is less than the energy absorbed, due to losses during the charge and discharge cycle. This makes not only the installed capacity important, but also the actual energy efficiency, the frequency of use and the operating conditions of each system.
The major challenge of financial viability
One of the key questions for the market is whether energy storage projects can secure sufficient revenues to cover their construction, financing and operating costs.
The ability to purchase or absorb energy at lower prices and sell it at higher prices can create commercial value. However, the outcome depends on price volatility, energy losses, available capacity and the specific way in which each facility participates in the market.
Therefore, the economic viability of each project must be assessed based on actual operating conditions and the revenue opportunities offered by the current regulatory framework. At the same time, accelerating investments requires clear rules and predictable procedures for grid connection and market participation.
The environmental dimension of energy storage
Investment evaluation does not end with installation and operation. Batteries are subject to environmental and regulatory requirements covering their entire lifecycle, from product safety and sustainability to collection, processing, and waste management.
European Regulation 2023/1542 on batteries and waste batteries establishes relevant obligations. Compliance with this framework is part of market design and operation, as the development of new installations must be combined with the responsible management of their materials and waste.
What will determine the next phase of battery development?
The Greek energy storage market is now called upon to turn intense licensing activity into real projects. This prerequisites timely grid connection, clear market participation terms and investment models that take into account actual technical and economic conditions.
The gap remains wide, given that out of the 65.3 GW of total capacity recorded in RAAEY’s licensing registry, a mere 1.6 GW concerns projects that have secured a connection offer or are already in operation on the transmission system, according to IPTO’s registry. Although the two figures relate to different dates and stages of development and are not directly comparable, they highlight just how vast the distance remains between licensing and implementation.
The issue now is how many of the licensed projects will ultimately reach connection and operation.